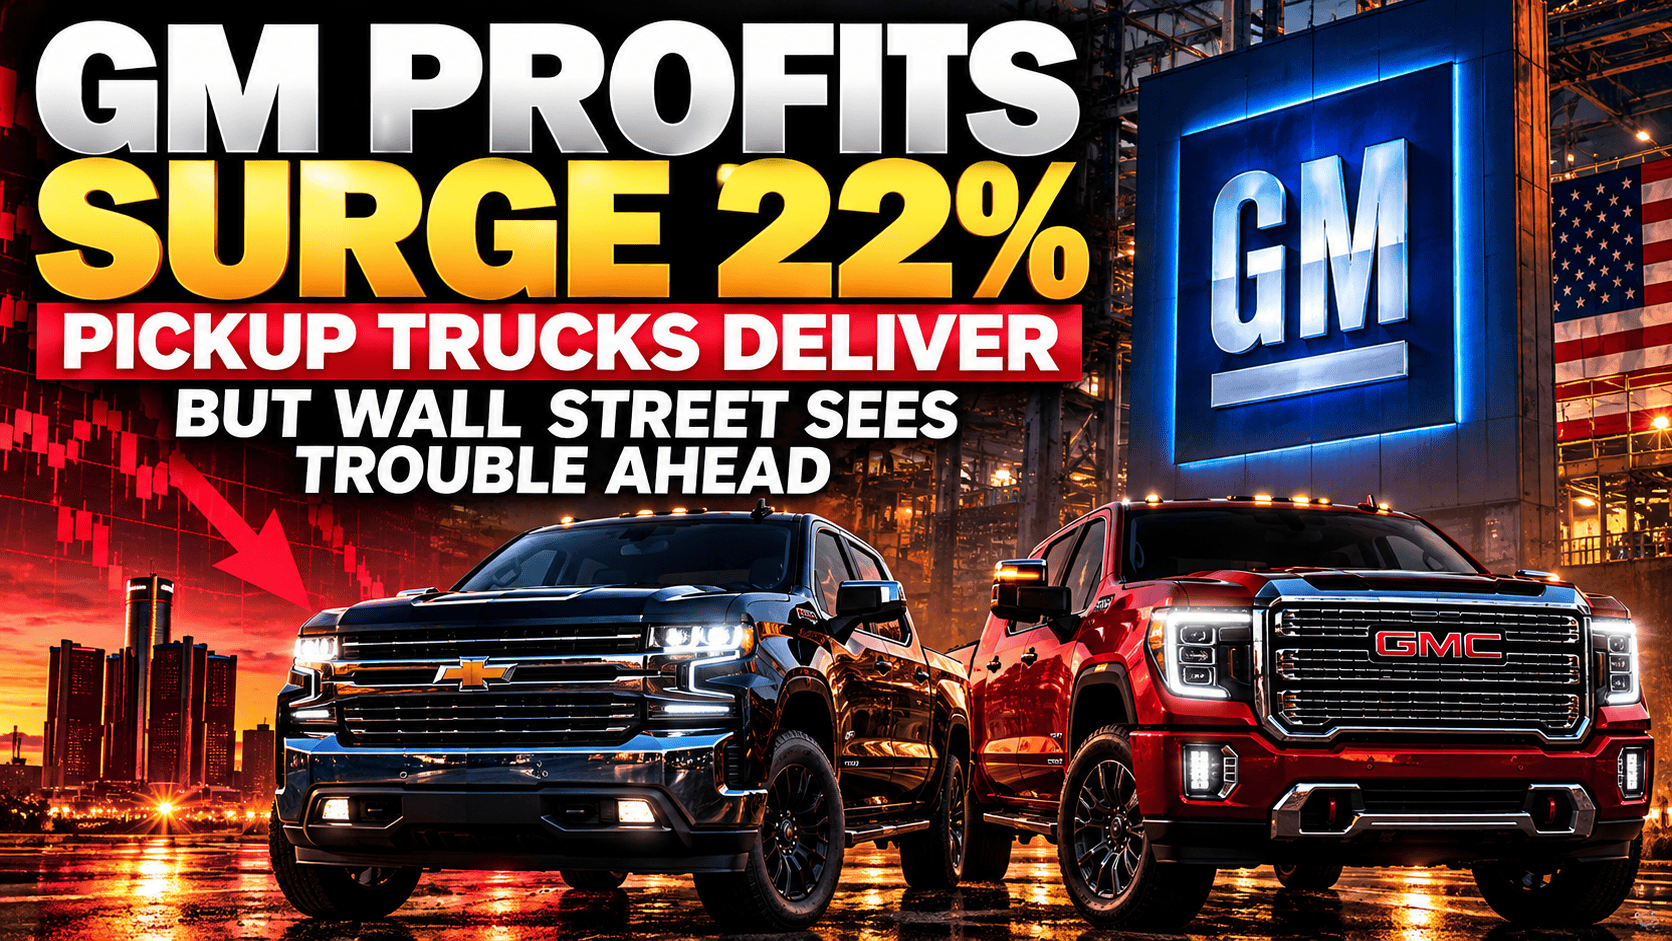
General Motors just delivered billions in quarterly profits, powered by America’s appetite for expensive pickup trucks. But behind the impressive numbers lies a more complicated story: rising costs, an uncertain electric vehicle transition, and investors who aren’t entirely convinced the good times will last.
Detroit’s Pickup Truck Empire Is Still Making Billions
DETROIT — General Motors has delivered another reminder that, despite years of promises about an electric future, traditional pickup trucks remain among the most powerful profit engines in the American automotive industry.
The Detroit automaker reported a 22% increase in third-quarter adjusted operating profit on Tuesday, October 20, reaching approximately $4.1 billion.
Revenue climbed to approximately $50 billion, an increase of 2.9% compared with the same period last year.
On paper, the results look impressive.
GM exceeded Wall Street’s quarterly earnings expectations, supported by strong demand for large pickup trucks and SUVs.
But financial markets weren’t celebrating.
GM shares fell approximately 4% in premarket trading after the company’s full-year earnings outlook failed to satisfy investors.
And that reaction reveals something important about the automotive industry.
______________________________________________
🔴 Help keep this independent voice alive and uncensored.
Support independent journalism and help keep Chris Wick News going.
👉 Support Chris Wick on GoFundMe
Making billions isn’t necessarily enough anymore. Investors want proof that the profits will keep coming.
The Pickup Truck Is Still King
For years, the automotive industry has been told that electric vehicles represent the future.
Billions of dollars have been committed to battery technology, manufacturing facilities, and entirely new vehicle platforms.
Governments have introduced incentives and regulations intended to accelerate the transition away from traditional gasoline-powered vehicles.
Yet GM’s latest financial results reveal something that should make industry executives pay attention.
Americans are still spending heavily on conventional trucks.
Models such as the Chevrolet Silverado and GMC Sierra remain central to GM’s business, delivering financial returns that have historically been difficult to achieve with electric vehicles.
GM reported that its North American profit margin improved to approximately 8.7%, compared with 6.2% a year earlier.
The improvement came despite a slight decline in quarterly vehicle sales.
That distinction matters.
GM didn’t necessarily need to sell more vehicles to generate significantly stronger profits. Selling a more profitable combination of vehicles helped deliver the results.
The trucks that some policymakers want to see gradually replaced are still helping finance the industry’s future.
The Electric Vehicle Reality Check
The company’s performance also highlights a difficult economic reality facing the electric vehicle industry.
GM sold a smaller proportion of electric vehicles during the quarter, contributing to improved profitability because its EV operations have historically generated weaker returns.
The Trump administration’s withdrawal of federal support for electric vehicles has added another challenge to the market.
For automakers that invested enormous sums anticipating sustained government incentives and accelerating consumer adoption, the shifting policy environment has complicated long-term planning.
But the larger question extends beyond Washington.
What happens when government ambitions collide with what consumers actually want to purchase?
GM’s results suggest that buyers of large, profitable gasoline-powered vehicles continue to play a crucial role in financing the company’s operations and future investments.
That doesn’t mean electric vehicles are disappearing.
It doesn’t mean consumers have rejected electric transportation altogether.
And it certainly doesn’t mean battery technology has no future.
What it does mean is that the transition is proving more complicated than some of the industry’s earlier predictions suggested.
Automakers must balance long-term technological investments against the immediate financial realities of running enormous manufacturing businesses.
GM continues investing in future technologies while relying heavily on its established truck business to generate cash.
That creates a fascinating contradiction.
The future of the electric vehicle industry may depend partly on the profits generated by gasoline-powered trucks.
Wall Street Isn’t Buying the Entire Success Story
Despite beating quarterly earnings expectations, GM’s stock came under pressure.
The company reported adjusted earnings of $3.70 per share, above the $3.63 expected by analysts surveyed by LSEG.
However, GM narrowed its projected full-year adjusted earnings to between $12.75 and $13.75 per share.
The midpoint of that range, $13.25, was below Wall Street’s consensus estimate of $13.41.
GM also tightened its full-year adjusted operating profit forecast to between $14.5 billion and $15.5 billion.
The previous range had been $14 billion to $16 billion.
That represents a narrower forecast rather than a clear increase in expected annual operating earnings.
Investors appear to be looking beyond one profitable quarter and questioning how much additional growth GM can deliver as economic pressures build.
The market’s reaction also demonstrates an uncomfortable reality for major corporations.
Strong performance doesn’t always produce investor enthusiasm when expectations are even stronger.
GM delivered substantial profits.
Wall Street wanted more.
A $20 Billion Message to Shareholders
Perhaps one of the most revealing announcements wasn’t about vehicle sales at all.
GM’s board authorized a new $20 billion multiyear share repurchase program.
The company has already repurchased approximately $29.5 billion of its own shares since 2023.
Share buybacks reduce the number of outstanding shares, potentially increasing earnings per share and returning capital to investors.
GM presents the latest authorization as evidence of confidence in its long-term financial performance.
And it may well be.
But it also raises an interesting question.
When an automaker commits $20 billion to buying back its own stock, what does that say about its priorities?
Supporters argue that returning excess capital to shareholders is a legitimate and efficient use of company resources.
Critics question whether enormous repurchase programs should receive priority when manufacturers face substantial investment requirements, changing technologies, and affordability concerns.
Both arguments deserve examination.
It is also important to understand that a buyback authorization doesn’t mean the entire $20 billion will be spent immediately.
It gives the company permission to repurchase shares over time.
Still, the sheer size of the authorization illustrates the financial power of one of America’s largest automakers.
And it raises a broader question about how corporate profits are distributed between investors, employees, innovation, and consumers.
Inflation, Tariffs and the Costs Nobody Can Ignore
GM’s profitability doesn’t make the company immune to economic pressure.
The automaker expects approximately $2 billion in commodity-related inflation and other cost increases this year, including expenses associated with logistics and computer chips.
Tariffs and higher energy costs are also creating challenges.
These pressures matter because the automotive industry operates within a complicated international supply chain.
Parts, materials, electronics, and completed vehicles frequently cross national borders before reaching dealerships.
Even a company with strong sales can face shrinking margins when those costs rise.
And for consumers already confronting expensive vehicle prices and financing costs, there is a limit to how much additional expense manufacturers can pass along.
A pickup truck that once represented practical transportation for working families has increasingly become a major financial commitment.
Higher purchase prices, insurance premiums, fuel expenses, and borrowing costs all contribute to the burden.
Manufacturers may continue generating impressive profits from premium vehicles, but affordability remains a serious question.
How long can automakers keep pushing vehicle prices higher before ordinary buyers begin walking away?
GM expects improved financial performance in 2027, but that outlook depends partly on continued consumer demand and moderating cost pressures.
What GM’s Results Mean for Canada
For Canadian consumers, GM’s earnings provide a useful glimpse into the economics behind the vehicles sitting on dealership lots.
Pickup trucks and SUVs remain important products throughout Canada, particularly in communities where vehicles serve as work equipment, family transportation, and everyday necessities.
In rural Ontario, the Prairies, and many smaller Canadian communities, trucks aren’t simply luxury purchases.
They are frequently used for construction, agriculture, towing, transportation, and daily work.
But the financial pressures facing Canadian buyers are substantial.
Vehicle financing rates, insurance premiums, exchange-rate effects, and taxes can significantly increase the total cost of ownership.
GM’s reported earnings figures are in U.S. dollars and reflect its broader corporate operations, not a separate measure of Canadian dealership profitability.
A profitable manufacturer doesn’t automatically translate into more affordable vehicles.
Indeed, strong demand for higher-priced models can give automakers an incentive to prioritize vehicles that generate larger margins.
That creates a difficult balance between shareholder returns and consumer affordability.
For Canadian consumers, the important question isn’t simply whether General Motors is making money.
It’s whether the vehicles people actually need will remain financially accessible.
Detroit’s Future Is Being Financed by Its Past
General Motors is not abandoning new technology.
The company continues preparing next-generation Chevrolet Silverado and GMC Sierra pickups while developing advanced driver-assistance systems, autonomous technology, and new battery platforms.
But its latest earnings underline a central contradiction in the automotive industry’s transformation.
The established products that manufacturers are frequently encouraged to move beyond remain essential to financing the technologies intended to replace or complement them.
Traditional trucks are helping generate the cash.
Future technologies are competing for that cash.
And shareholders expect returns along the way.
The challenge is not simply deciding what vehicles to manufacture.
It is deciding how quickly the industry can change without damaging the profitable businesses that support it.
That question extends beyond General Motors.
Ford, Stellantis, and other global manufacturers face their own versions of the same dilemma.
Invest too slowly in emerging technology, and they risk falling behind competitors.
Invest too aggressively before consumer demand fully develops, and they risk undermining profitability.
There is no simple solution.
And despite the confident predictions that often accompany major technological shifts, the market ultimately has a way of testing corporate assumptions.
The Bottom Line: The Trucks Are Paying the Bills
GM’s 22% quarterly profit increase is a significant financial achievement.
But the numbers tell two different stories.
One is about a powerful American manufacturer generating billions of dollars from vehicles consumers continue to buy.
The other is about an industry navigating uncertain demand, rising costs, changing government policies, and enormous investment commitments.
For now, pickup trucks remain a cornerstone of GM’s profitability.
The company can celebrate its earnings.
Shareholders can debate whether the outlook is strong enough.
And policymakers can continue arguing over the future of transportation.
But the financial results deliver a message that is difficult to ignore.
Detroit’s electric future is still being financed, in substantial part, by the gasoline-powered vehicles of today.
The question isn’t whether electric vehicles will have a place in the future.
It’s whether automakers can afford the speed of the transition they once promised — and whether consumers are willing to pay for it.
Sources
Reuters — GM Shares Sink as Full-Year Profit Forecast Misses Wall Street Estimates (October 20, 2026) https://www.reuters.com/business/autos-transportation/gms-core-profit-rises-22-strength-pickup-truck-business-2026-10-20/
General Motors — Q3 2026 Press Release and Financial Highlights https://investor.gm.com/static-files/c79ce1e6-c1f9-41cc-b503-1b98e1dbdfb2